Collateral valuation is the appraiser’s opinion of value for an asset that is being used as security. In plain English, it helps a lender, owner, attorney, or insurer understand what a piece of equipment or a fleet is worth for a specific purpose on a specific effective date.
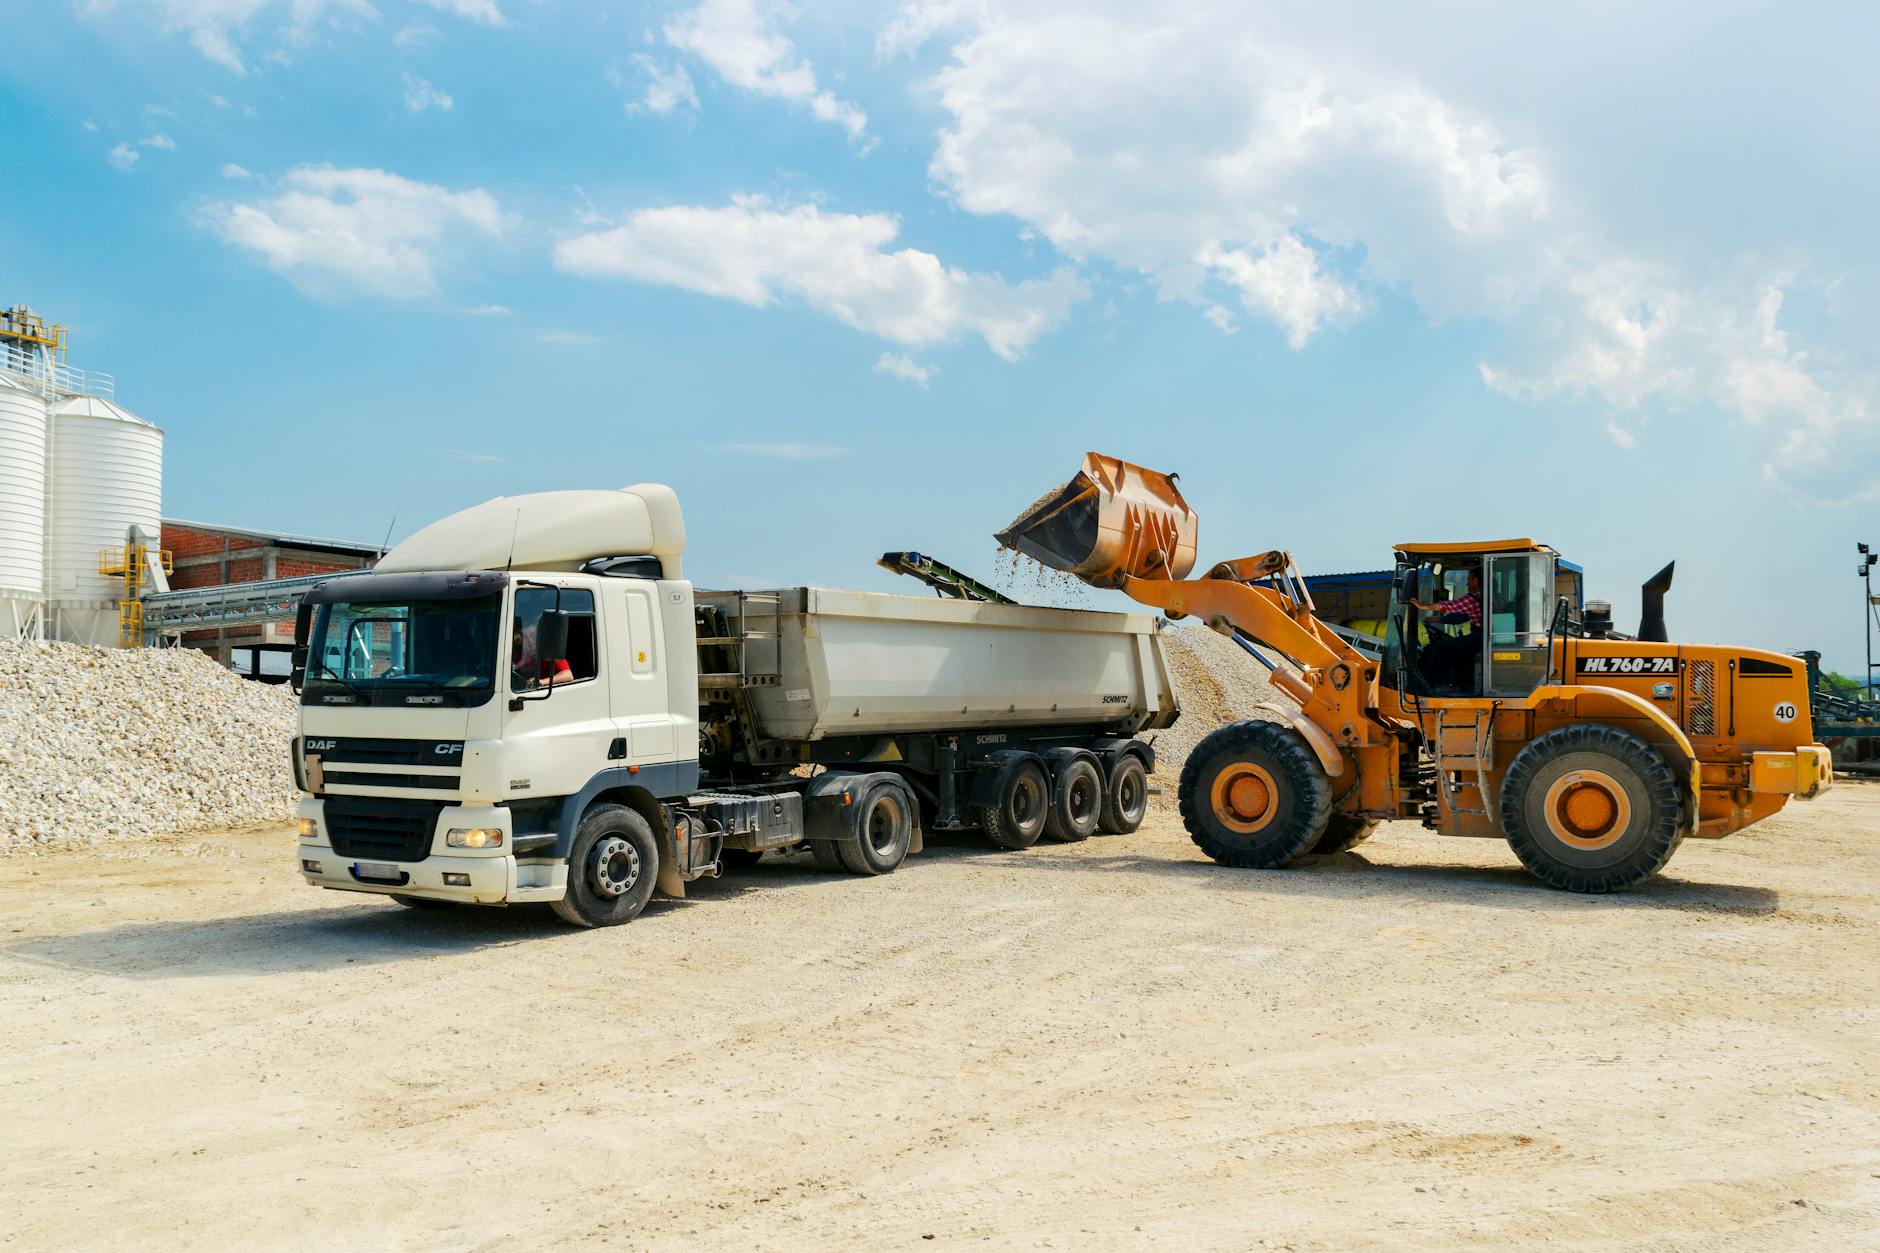
For hard assets like construction equipment, trucks, tractors, and specialty vehicles, the answer is not just a number pulled from a listing site. A credible collateral valuation ties the asset to its identity, condition, market evidence, and the premise of value being used. That is the difference between a loose estimate and a defensible appraisal.
The basic definition and why lenders rely on it
Collateral valuation is an appraisal analysis used to support a secured transaction. The asset is serving as collateral, which means its value matters to the lender if the loan depends on that property for credit support.
Lenders rely on collateral valuation to understand lending risk, loan structure, advance rates, and whether the asset can reasonably support the transaction. A well-supported opinion helps underwriting teams make decisions with better facts, especially when the collateral is used equipment rather than new equipment with a dealer invoice.
In practice, the appraiser is not deciding whether the loan should be made. The appraiser is documenting the asset, selecting the correct basis of value, and supporting an opinion with market evidence. If you want a broader look at how these assignments fit into equipment lending, see our equipment financing appraisal services.
What an appraiser examines when valuing collateral
A collateral valuation starts with the asset itself. The appraiser identifies the make, model, year, serial number or VIN, configuration, usage history, hour or mileage readings, and any attachments or accessories that materially affect utility. Ownership and title details also matter because the appraiser needs to know exactly what is being valued.
Condition is just as important. Wear, maintenance, repairs, damage, modifications, and functional issues all affect value. A machine that runs well but has structural damage, missing components, or an unusual setup may not track with a clean comparable sale.
The market evidence comes next. Appraisers study actual transactions, auction results, dealer asking prices, and other relevant sales data, then reconcile that evidence against the subject asset. For a closer look at the mechanics of this process, read our guide on how machinery and equipment valuation works.
Asset identification, condition, and ownership details
Good collateral work begins with correct identification. If the model year, series, capacity, or configuration is off, the conclusion can drift away from the real asset. That is why inspection notes, photos, and documentation are part of the file, not an afterthought.
Ownership matters too. An appraiser needs to understand what interest is being valued and whether there are liens, lease terms, or title questions that affect the assignment. The appraisal does not solve the legal issue, but it does need to recognize the facts that are known and relevant to the value opinion.
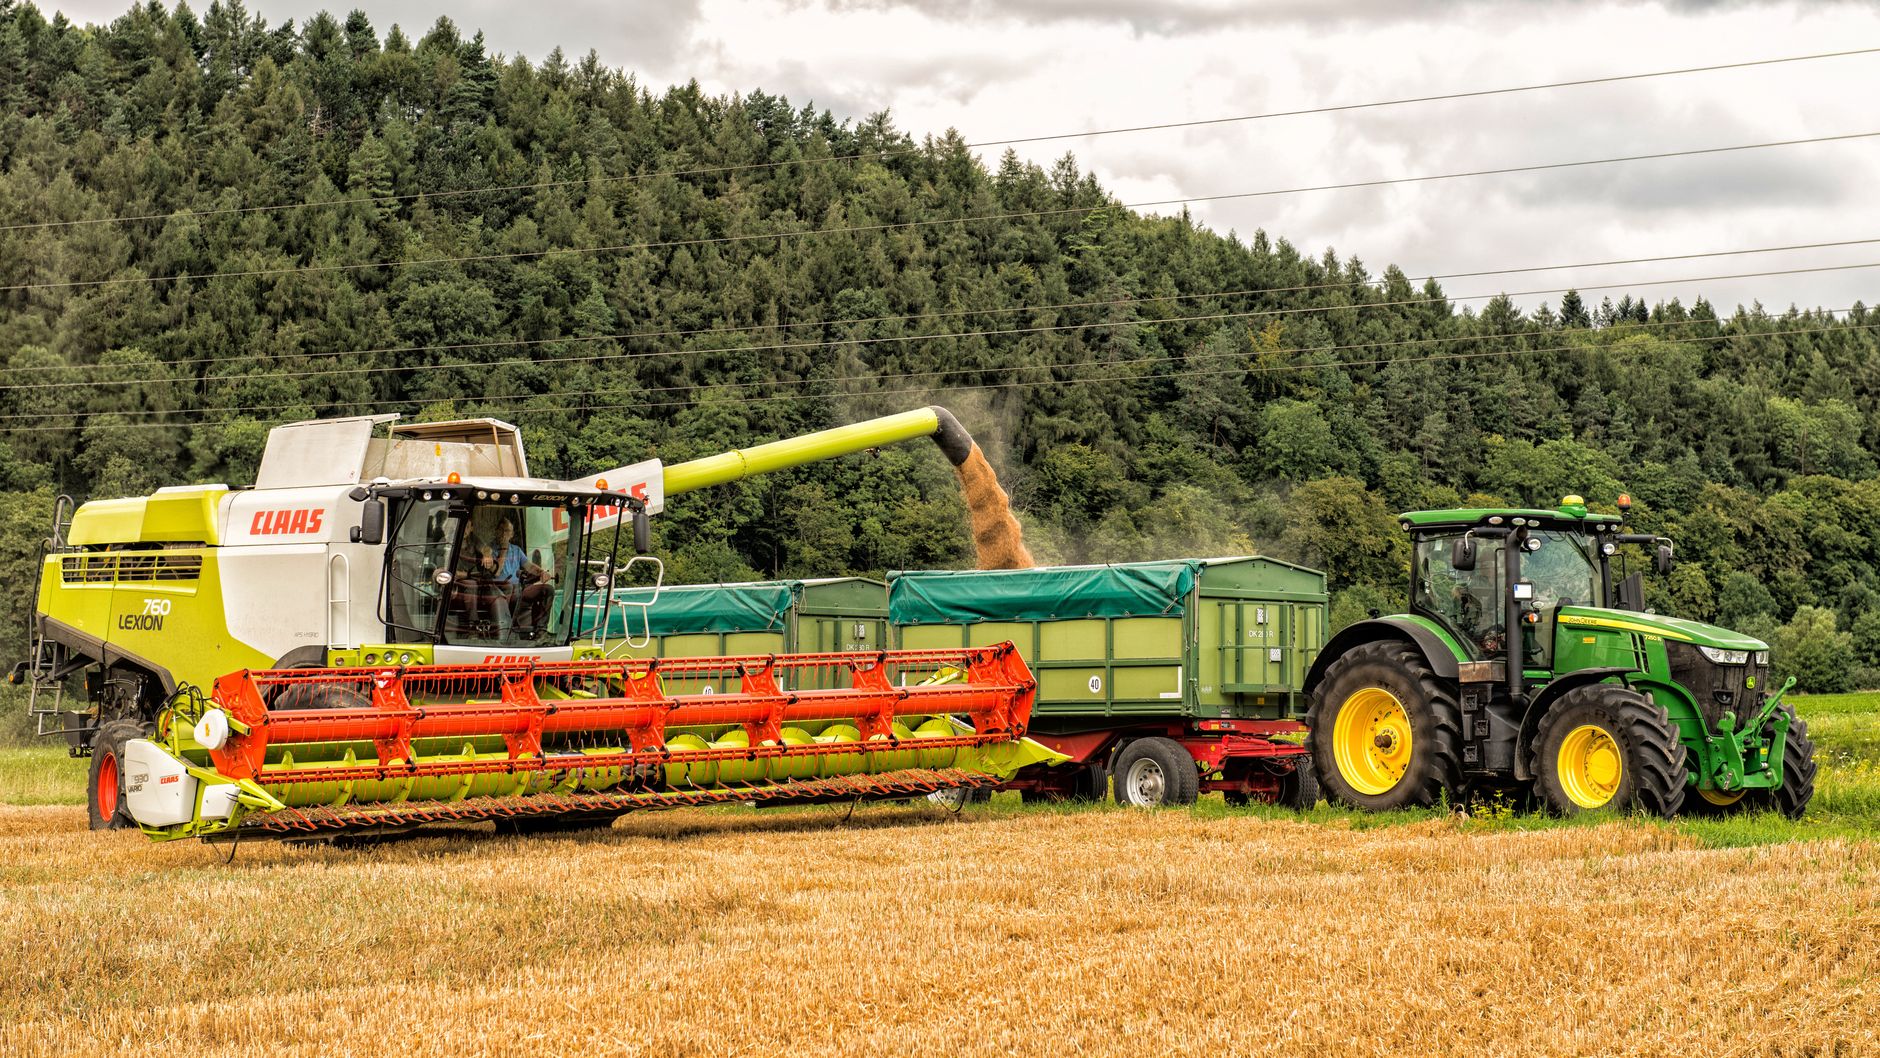
For lenders and owners, this is where collateral valuation becomes practical. A tractor with strong maintenance records and complete documentation may support a very different conclusion than the same model with uncertain hours, visible wear, or incomplete ownership records.
- Correct identity: make, model, year, serial number, and configuration
- Physical condition: wear, damage, maintenance, and repairs
- Operating status: running, idle, stored, or out of service
- Documentation: title, liens, leases, photos, and inspection notes
Market data, auction results, and comparable sales
Collateral valuation is market-based, not opinion-based in the casual sense. The appraiser looks for the best available evidence of what similar assets have actually sold for, then adjusts for differences in age, condition, usage, and specification.
For equipment and fleets, auction results can be especially useful because they show real-world pricing under a defined market setting. Dealer sales, private transactions, and listings can also inform the analysis, but they have to be weighed carefully. A asking price is not the same thing as a sold price, and not every sale reflects the same market premise.
That is why context matters. A machine may support one value conclusion in a liquidation scenario and a different conclusion in an orderly market scenario. If you are sorting through the difference between collateral work and forced-sale analysis, our article on what liquidation value means can help frame the distinction.
Common collateral valuation purposes beyond lending
Although lenders are the most common users, collateral valuation shows up in several other settings. Business owners may need it for a sale, partnership change, refinance, or internal planning decision. Attorneys and accountants may need a defensible value for litigation, bankruptcy, estate administration, or tax-related reporting.
Insurance professionals also use valuation analysis to align coverage with the asset base, although insurance value is its own subject and should not be confused with lending collateral value. The reason for the assignment drives the definition of value, the effective date, and the approach to support.
If your assignment is tied to a secured loan or refinance, it is usually helpful to start with the asset list and the intended use of the report. You can also review our appraisal services to see how Jeff Martin Appraisals structures equipment and fleet engagements.
- Loan origination and refinance decisions
- Partnership changes and buyout support
- Litigation, estate, and bankruptcy matters
- Insurance planning and asset review
How collateral value differs from market value, liquidation value, and insurance value
People often use “value” as if it means one thing, but appraisal work depends on the premise of value and the purpose of the assignment. Collateral value is not always the same as market value, liquidation value, or insurance value. Those terms may overlap in conversation, but they do not carry the same assumptions.
Market value generally reflects a normal sale between informed parties under typical conditions. Liquidation value assumes a faster or more pressured sale setting. Insurance value is usually tied to coverage needs and replacement considerations, which can point in a different direction than lending analysis. Collateral value may lean on one of these premises, or it may be defined more specifically by the engagement.
This is why the report has to name its effective date and premise of value clearly. Without that, a value conclusion can be misunderstood and misused, which is a problem for lenders, owners, and counsel alike.
What makes a collateral valuation defensible and USPAP-compliant
A defensible collateral valuation is built on a clear assignment definition, credible inspection or documented identification, relevant market evidence, and an explanation of how the conclusion was developed. That is the framework lenders and counsel expect when the report may be reviewed, audited, or challenged.
USPAP compliance matters because it gives the work product structure, disclosure, and accountability. It does not guarantee that everyone will agree with the conclusion, but it does mean the appraiser has followed recognized standards for problem identification, scope of work, analysis, and reporting.
For equipment and fleet assignments, that also means the appraiser stays within the asset class and does not overreach. A valuation should reflect the actual property analyzed, not a generic market average. When the file is complete, the conclusion is easier to defend because the path from asset facts to final opinion is visible.
- Clear assignment conditions and intended use
- Correct premise of value and effective date
- Inspection, photos, and identifying information
- Relevant market data with reasoned adjustments
- Reporting that supports review and challenge
When to contact Jeff Martin Appraisals
If you need collateral valuation for equipment, trucks, tractors, or a fleet, the best first step is to describe the asset and the purpose of the valuation. Jeff Martin Appraisals can help determine the right scope for a USPAP-compliant engagement and the kind of analysis the assignment calls for.
If you are not ready to speak with someone yet, the Value Estimator is a lower-friction way to start organizing the asset details. But if the valuation will support a loan, secured transaction, dispute, estate matter, or other formal purpose, a direct conversation is usually the better path.
The more precisely you can identify the asset and explain why the valuation is needed, the easier it is to build a report that stands up to review. Jeff Martin Appraisals is ready when you are.
Questions We Get Asked
What does collateral valuation mean in lending?
In lending, collateral valuation is the appraiser’s opinion of what an asset is worth for a secured transaction. The value depends on the asset, its condition, the market evidence, the intended use, and the defined premise of value.
Is collateral valuation the same as market value?
Not always. Market value is one possible premise, but collateral assignments may require a different lens depending on the transaction. The report should name the premise of value and the effective date so the conclusion is not misread.
What assets can be used for collateral valuation?
At Jeff Martin Appraisals, collateral valuation commonly applies to equipment, fleets, trucks, tractors, and other hard assets. The assignment has to fit the property type and the intended use of the appraisal.
Why is USPAP compliance important?
USPAP compliance gives the appraisal a recognized professional structure. It helps ensure the assignment is properly defined, the scope of work is appropriate, and the report can be reviewed with confidence by lenders, attorneys, owners, and other users.