Orderly liquidation value is a specific appraisal premise, not a guess at what something might bring if it has to move quickly. It assumes the asset will be sold in an organized way, under stated conditions, within a reasonable exposure period.
For lenders, attorneys, business owners, and insurers, the point is defensible support. The conclusion has to match the intended use, the effective date, and the market conditions the appraiser is analyzing.
Orderly liquidation value, defined in appraisal terms
In appraisal work, orderly liquidation value (OLV) is the estimated amount that a property would realize under a liquidation scenario, but without the pressure and disorder of a fire sale. The asset is assumed to be exposed to the market for a normal or reasonable marketing period, with a seller who is motivated but not forced into immediate disposal.
That distinction matters because OLV is not the same as a retail price, a dealer asking price, or a balance sheet number. It is an opinion of value developed from market evidence and a clearly stated premise of value. In plain terms, the appraiser asks: what would a typical market participant pay if the asset were sold in an orderly, managed liquidation?
For a broader look at related terms, see our guide on what liquidation value means in appraisal practice.
How orderly liquidation value differs from fair market value and forced liquidation value
Fair market value assumes a willing buyer and willing seller, both typically informed and neither under undue compulsion. OLV usually sits below fair market value because the sale context is narrower and the seller is disposing of the asset rather than holding it for continued use.
Forced liquidation value is different again. It reflects a more urgent sale condition, often with compressed exposure, reduced buyer access, and less room to negotiate. That usually puts the conclusion below OLV because time and process are constrained.
If you want a related operational perspective, our article on how machinery and equipment valuation works explains how appraisers support these conclusions with market data and condition analysis.
- Fair market value: normal market exposure, no compulsion.
- Orderly liquidation value: managed sale, reasonable exposure, disposal context.
- Forced liquidation value: accelerated sale, limited exposure, more pressure on price.
Why the assumed sale timeline matters
A defensible OLV conclusion does not just say the asset is being liquidated. It explains how long the asset is assumed to be available, who can see it, and what the seller is expected to do to reach the market. Those details drive the analysis as much as the equipment itself.
That is why lenders and attorneys often ask for OLV instead of a generic “quick sale” estimate. They need a defined scenario they can explain, defend, and compare to other collateral or estate assets.
Why buyer access, exposure, and sale conditions matter
An appraiser does not simply subtract a standard percentage and call it OLV. The analysis is tied to the asset, the market, and the assumed sale setting. That is what makes the conclusion defensible in lending, legal, and ownership disputes.
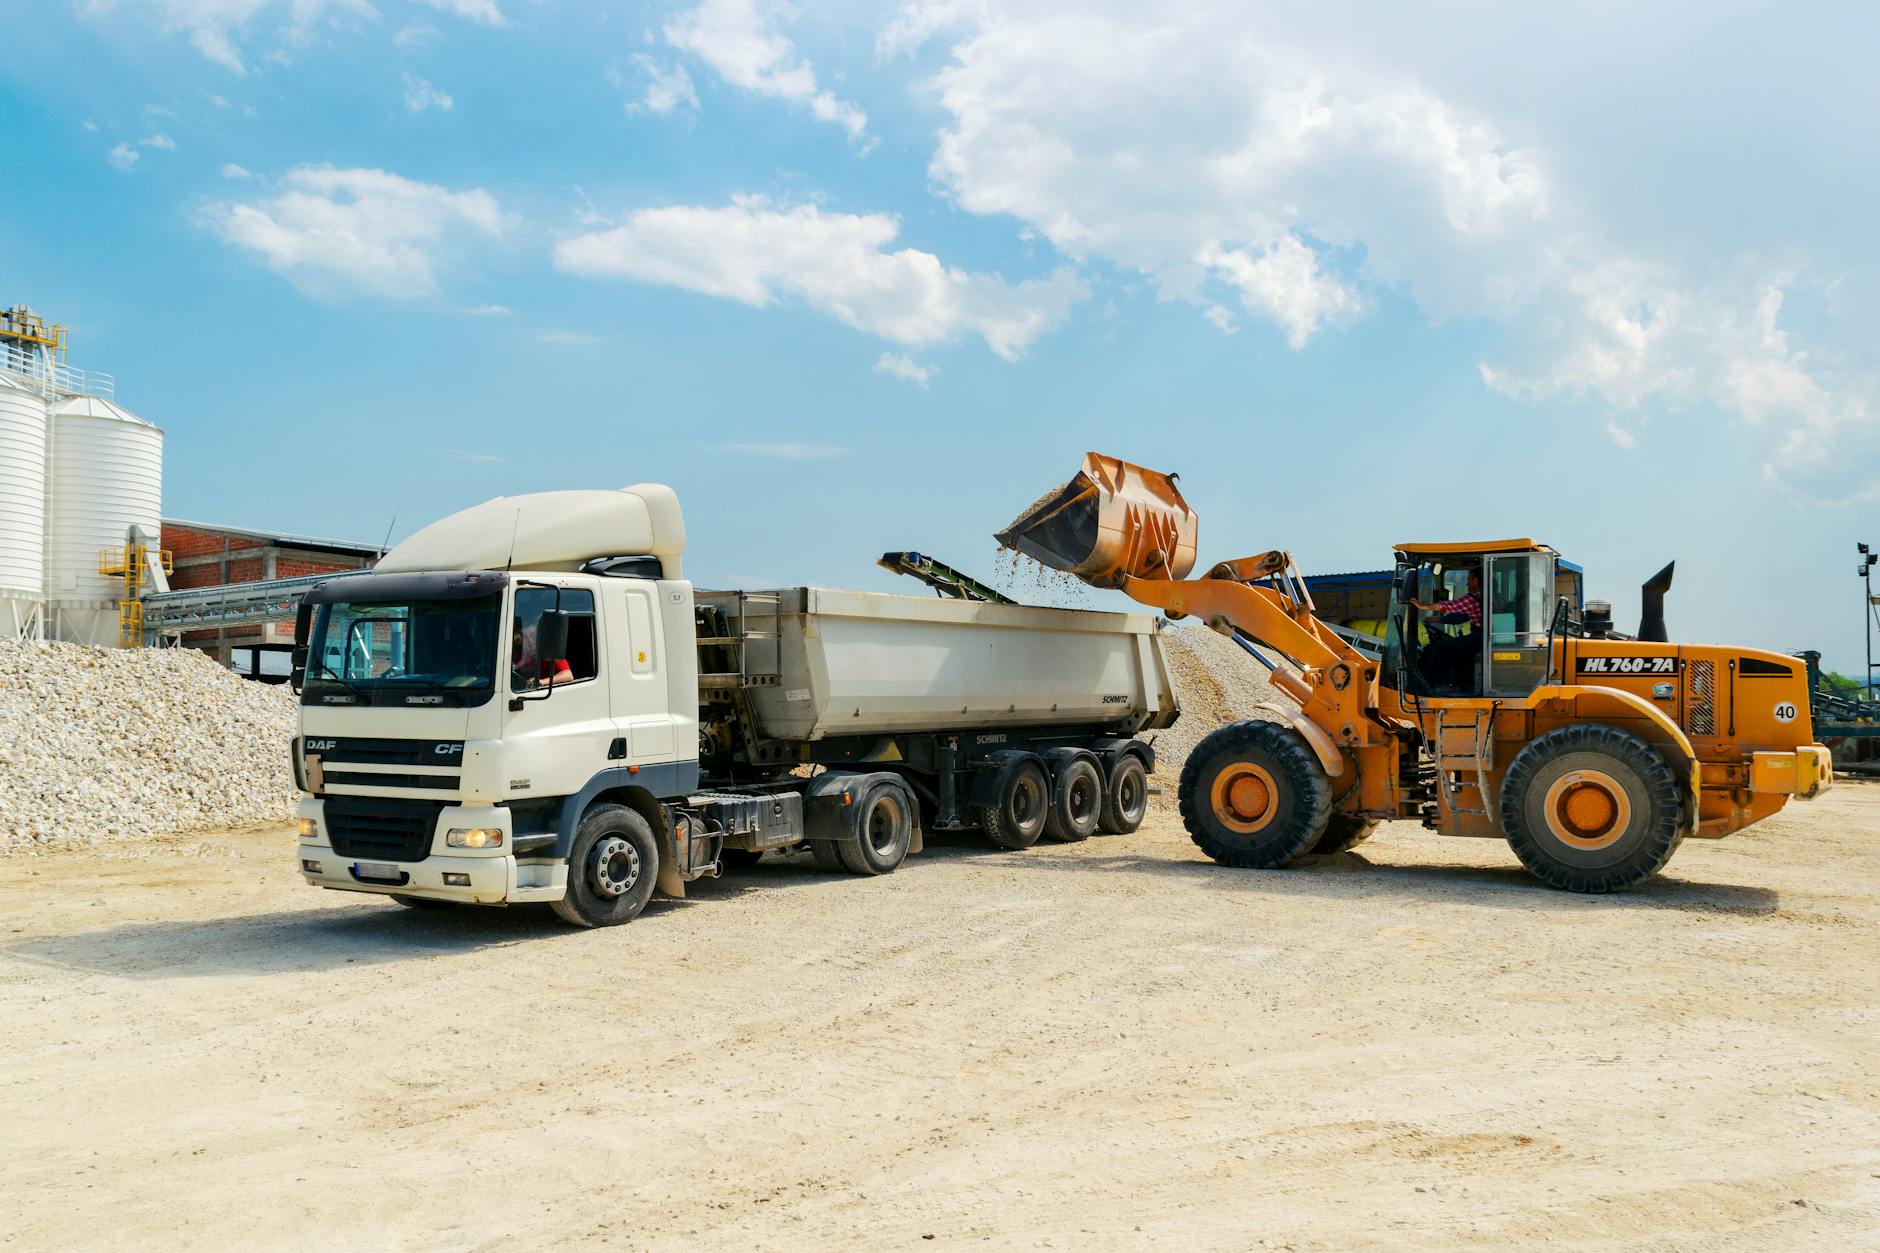
For heavier equipment and mobile assets, buyers often care about hours, maintenance records, configuration, and transport burden. Those practical details can influence both marketability and the range of buyers willing to make an offer.
What appraisers examine when developing an orderly liquidation value conclusion
The appraiser also considers the likely buyer pool. Some assets attract end users, while others mainly appeal to dealers, contractors, or fleet buyers. The more constrained the buyer pool, the more important it is to support the conclusion with good market evidence and a clear explanation of the sale scenario.
When the asset is a truck, trailer, or mixed fleet unit, the analysis may depend on use class, mileage, wear, and geographic demand. When it is agricultural equipment, the buyer pool can depend heavily on seasonality, machine type, and local working conditions. That is why assignment scope matters so much in appraisal work.
- Asset type and model
- Condition, age, and operating status
- Maintenance and service records
- Current market demand
- Compatibility with likely buyers
- Transportation, removal, and sale costs
- The assumed liquidation setting and exposure period
Common situations where lenders, attorneys, and owners request OLV
Insurance professionals may also look at related value concepts when setting coverage or reviewing replacement exposure, although the premise used in insurance work is often different from OLV. The key is that the report should match the policy question, not just the asset class.
In every case, the assignment should be set up before the analysis begins. The intended use shapes the premise of value, the market data selected, and the way the conclusion is communicated.
What a defensible OLV report should include
A defensible report should identify the asset, state the effective date, define the premise of value, and explain the sale conditions assumed in the analysis. It should also describe the inspection performed, the data sources used, and the reasoning that connects the market evidence to the final conclusion.
The report should not leave the reader guessing about whether the asset was inspected, whether the comp set was relevant, or whether the conclusion reflects a normal sale, a distressed sale, or some other premise. In litigation or lending work, those details are not optional. They are part of the support.
At minimum, readers should expect clear identification, transparent methodology, relevant comparable data, and an explanation of any major adjustments or limiting conditions. Without that structure, the conclusion is hard to defend and easy to challenge.
- Asset identification and inspection details
- Effective date and premise of value
- Assumed sale conditions and exposure period
- Market data and comparable sales support
- Explanation of adjustments and key assumptions
- Limiting conditions and intended use
When to contact Jeff Martin Appraisals for an orderly liquidation value engagement
When you are ready to move forward, describe the asset and the reason you need the valuation through Jeff Martin Appraisals. Include the asset type, the number of units if there is more than one, the purpose of the appraisal, and any timing or access constraints that matter to the assignment.
Clear input leads to a better scoped engagement. That is the simplest way to get an orderly liquidation value conclusion that is practical, defensible, and suited to the real question being asked.
Questions We Get Asked
Is orderly liquidation value the same as liquidation value?
Not exactly. The term liquidation value is often used loosely, but orderly liquidation value specifically assumes an organized sale with reasonable exposure to the market. Forced liquidation value is more urgent and usually reflects a more compressed sale setting.
When would a lender ask for orderly liquidation value?
A lender may ask for OLV when equipment, fleet assets, or other business assets are serving as collateral and the lender wants to understand downside support under a managed disposition scenario. The value premise should match the credit question being asked.
Does an orderly liquidation value appraisal require an inspection?
In most assignments, yes. An inspection helps the appraiser verify identity, condition, configuration, and other factors that affect marketability. The scope should always fit the assignment and be stated clearly in the report.
Can orderly liquidation value be used for estate or bankruptcy work?
Yes, when the assignment calls for a liquidation premise and the intended use supports it. The appraiser should still define the effective date, the sale assumptions, and the market evidence used to support the conclusion.