Forced liquidation value is not a generic estimate of what an asset might bring. It is a value opinion built around a pressured sale premise, where the appraiser has to consider limited time, limited exposure, and the likely buyer pool under those conditions.
That matters to lenders, attorneys, owners, and insurers because the premise of value controls the result. If the assignment does not define the effective date, intended use, and sale scenario, the number can be easy to misread and hard to defend.
What forced liquidation value means in an appraisal context
Forced liquidation value describes what an asset might reasonably sell for when time is tight and the seller cannot wait for a broad, normal marketing process. The point is not to predict the best possible outcome. The point is to reflect a sale environment where pressure tends to limit negotiation and reduce proceeds.
In practice, that premise has to be stated clearly in the assignment. The appraiser should identify the asset, the effective date, the intended use, and the assumed disposition conditions so the reader knows exactly what the conclusion does and does not represent.
When lenders, attorneys, and owners use forced liquidation value
Lenders and credit professionals may need this premise when they are evaluating collateral recovery under stress. In that setting, the question is not what the equipment would bring in an ideal sale. The question is what recovery could look like if the asset has to move quickly and market exposure is limited.
Attorneys, accountants, and owners may also rely on this premise in bankruptcy, dispute, estate, or restructuring work. In those cases, the appraisal supports decision-making by framing downside value under a defined set of assumptions rather than trying to fit every possible use into one number.
- Collateral review for lending and underwriting
- Bankruptcy, dispute, or estate analysis
- Internal planning when a quick sale is possible
- Downside valuation for ownership or recapitalization decisions

How forced liquidation value differs from fair market value and orderly liquidation value
Fair market value assumes a willing buyer and willing seller, both reasonably informed, with normal exposure to the market and no pressure to act. Forced liquidation value sits at the distressed end of the spectrum. It assumes the seller is under time pressure and the sale environment is less favorable.
Orderly liquidation value is different from both. It still assumes a sale, but with more time and a more orderly marketing process than a forced sale. Because the assumptions are different, the conclusions can diverge significantly, especially for specialized equipment or assets with a narrow secondary market.
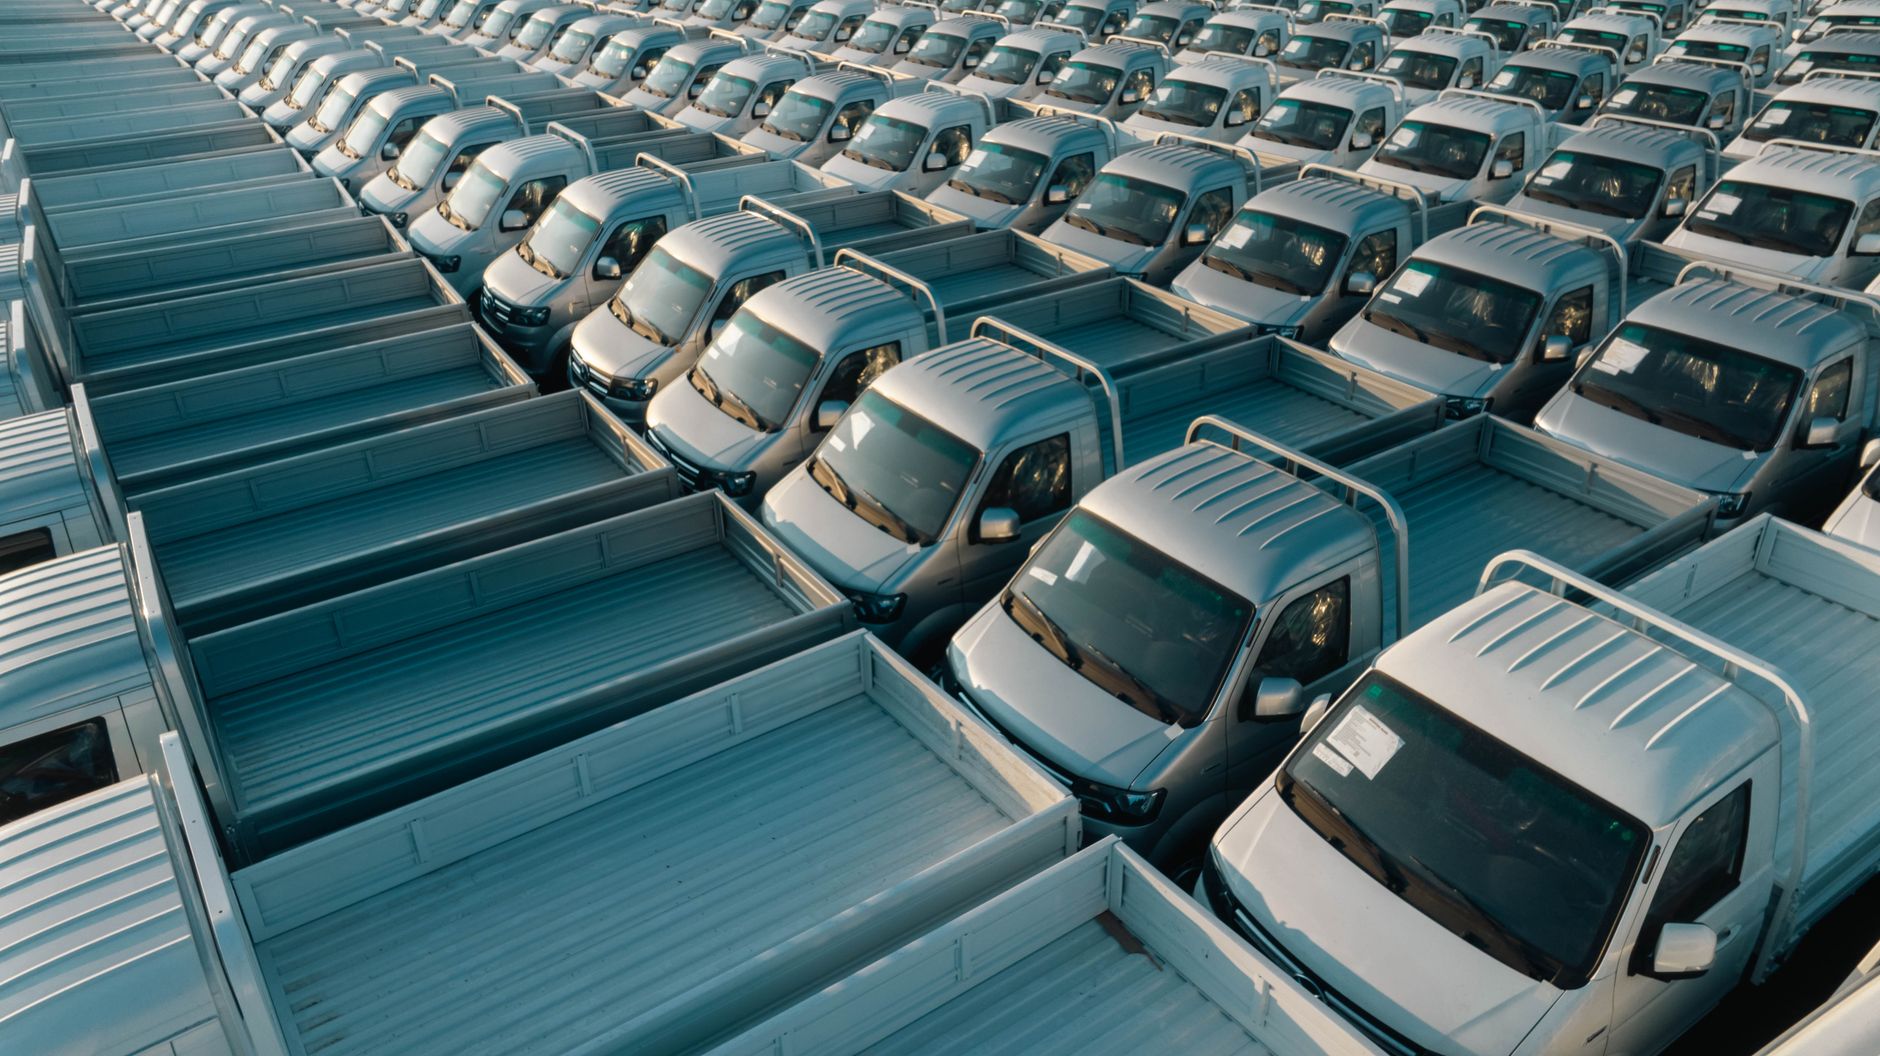
The factors that shape a forced liquidation conclusion
A forced liquidation conclusion is built from market evidence, not from a shortcut formula. The appraiser considers how the asset trades, what comparable sales show, and how much friction exists in getting the asset sold under the assumed timeline. The tighter the timeline, the more important those practical limits become.
Condition and marketability carry a lot of weight. An asset that is complete, operable, and well maintained is usually easier to place than one with missing components, visible wear, or unresolved mechanical issues. Age, hours, mileage, remaining utility, and demand for that specific asset type also influence the result.
- Asset type and how broad the buyer pool is
- Physical condition, completeness, and maintenance history
- Age, hours, mileage, and remaining utility
- Recent market sales and current demand
- How much time is available to market the asset
Why the intended use matters more than the label
The same asset can support different value conclusions depending on why the appraisal is being ordered. A lender may need a collateral-focused analysis. An attorney may need a value that fits a dispute or court process. An owner may want a clear read on downside exposure before making a business decision.
That is why intended use matters more than the phrase on the report cover. A USPAP-compliant appraisal starts with the problem to be solved, then matches the premise of value to that assignment. Without that connection, the conclusion may be difficult to defend or easy to misapply.
What a USPAP-compliant appraisal should document
A defensible report should show how the conclusion was formed, not just present a final number. It should identify the asset, the effective date, the intended use, the intended user, and the premise of value up front. It should also explain the market data, condition observations, and any limiting conditions that affect the opinion.
For a forced liquidation premise, that documentation should make the timing assumptions, exposure assumptions, and buyer pool assumptions visible. It should also explain why that premise was selected instead of fair market value or orderly liquidation value. That transparency is what helps the conclusion stand up in lending, legal, and internal review settings.
How to request a defensible liquidation value opinion
If you need a forced liquidation value opinion for an equipment, truck, trailer, or fleet asset, start by describing the asset and the reason for the valuation. The assignment purpose will shape the premise of value, the scope of work, and the way the report is prepared. Jeff Martin Appraisals works with lenders, owners, attorneys, accountants, and insurers who need a measured, USPAP-compliant conclusion.
If you are not ready to begin a formal engagement, the Value Estimator can be a lower-friction starting point. When you are ready to move forward, describe the asset and the intended use through Jeff Martin Appraisals so the assignment can be set up correctly from the start.
Questions We Get Asked
Is forced liquidation value the same as orderly liquidation value?
No. Forced liquidation value assumes more time pressure, less market exposure, and a more distressed sale setting than orderly liquidation value. Because the assumptions differ, the results can differ as well.
Why does condition matter so much in a forced liquidation appraisal?
Condition affects how quickly an asset can be sold and how many buyers will consider it. An incomplete, worn, or non-operational asset usually has a narrower buyer pool, especially when the sale must happen quickly.
Can forced liquidation value be used for lending decisions?
Yes, if that is the premise required by the assignment and the report is prepared for the lender’s intended use. The appraisal should clearly state the assumptions, effective date, and market evidence supporting the conclusion.